
FCA and Bank of England Set Out Route From Sandbox to Permanent Tokenised Market Rules After 123 Responses

Updated: 6 days ago
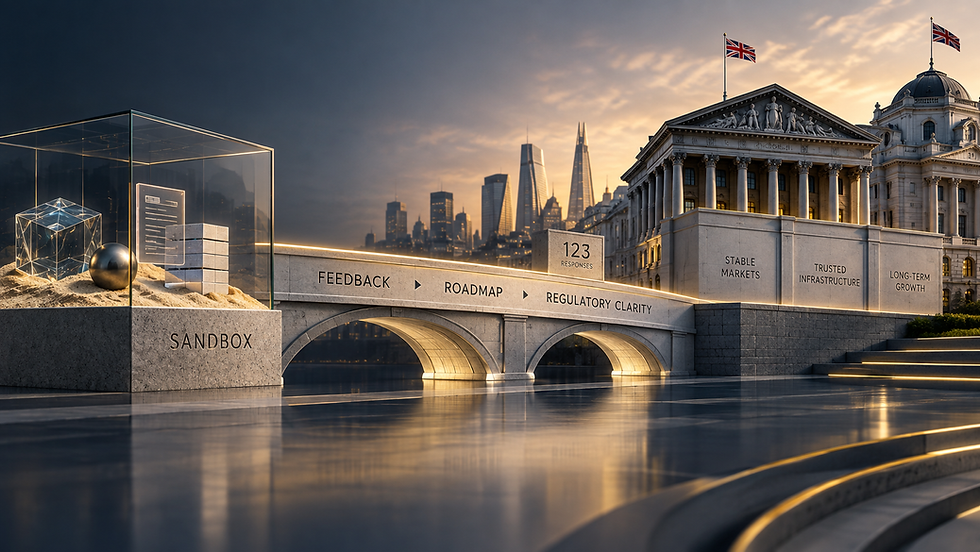
The Financial Conduct Authority and the Bank of England have committed to a clear route from the Digital Securities Sandbox to permanent tokenised market infrastructure, after industry told the regulators that pilots are no longer enough.
The two authorities published a joint Feedback Statement, FS26/1, on 14 September, summarising 123 responses to their May 2026 Call for Input on the future of tokenisation in UK wholesale financial markets. The respondents included banks, infrastructure providers, industry bodies, academics, many other market participants and Tokenisingstartups.com.
What happened
The feedback showed broad support for the regulators' direction of travel, but a consistent message came back on pace. Respondents asked for faster progress, clearer timelines, and a shift from time limited pilots to durable market infrastructure. The FCA said it will now publish a fuller roadmap later this year, setting out specific workstreams and target dates.
The areas the roadmap is expected to cover include digital securities issuance and settlement, tokenised assets and collateral, access to central bank money settlement, wider market functioning, custody of what the FCA terms relevant specified investment cryptoassets, and the Treasury's Digital Gilt Instrument pilot.
Respondents identified post-trade activity, and collateral management in particular, as the single biggest opportunity. The benefits cited included 24 hour trading, atomic settlement, greater collateral mobility and fewer reconciliation breaks. The FCA noted that tokenised collateral could improve collateral velocity and support real time margin calculations, and that tokenised money market funds could potentially be used as collateral without needing to be liquidated first.
The sandbox question
The clearest ask from industry was to move beyond sandboxes altogether. A recurring theme in the responses was a request for a long term model for digital securities settlement once the Digital Securities Sandbox ends. The FCA said it is committed to a clear path from the DSS to permanent authorisation, and will work with the Treasury to consider whether to extend or modify the sandbox, or amend the wider Central Securities Depositories Regulation framework that sits behind it.
HSBC has already been granted DSS permissions covering notary, top tier account maintenance and settlement functions, giving the regulators a live reference point as they design what comes next.
On regulatory philosophy, the FCA reaffirmed a technology neutral approach based on the principle of same risk, same regulatory outcome. Regulated activities must have an identifiable responsible firm attached to them, including where third party technology is being used underneath.
The regulator was also explicit about where it will not compromise. It said it would not support arrangements that leave customers with no recourse if assets are lost or stolen, and it flagged specific technical risk areas including bridges, key management, oracles, cross chain messaging and wallet security.
On prudential treatment, a live concern for banks weighing balance sheet impact, the FCA said tokenised versions of traditional assets should generally receive equivalent treatment to their non-tokenised counterparts, provided legal rights are identical and underlying risks are comparable.
Custody, stablecoins and interoperability
For custody of relevant specified investment cryptoassets, most respondents favoured a technology neutral regime broadly aligned with the FCA's existing CASS 6 client asset rules. The FCA plans to consult on safeguarding rules for this asset class in the first half of 2027; until then, firms operating in the space will continue to be assessed under CASS 6.
The FCA confirmed that stablecoins can be used within the DSS, subject to conditions and pending Treasury amendments. Industry also flagged interoperability, across different blockchains, jurisdictions and the older traditional infrastructure, as a major open concern, and the FCA said it expects industry itself to lead on the technical standards involved rather than mandating a single approach from the top down.
Direction of travel
This is the clearest signal yet that the UK intends to treat tokenisation as a permanent feature of wholesale market infrastructure rather than a contained experiment. The commitment to a published roadmap, with workstreams and target dates, is a direct response to warnings earlier this month, including from techUK chair Bob Wigley, that the UK risks ceding control of tokenisation rules to the US unless it moves with more urgency.
The FCA published a second, related piece of work on the same day: a separate Call for Input specifically on tokenised gold, covered elsewhere on Tokenising Startups. Taken together, the two publications point to a regulator extending its wholesale tokenisation thinking beyond securities and into other asset classes where London already holds a structural advantage.
What the Feedback Statement does not yet resolve is how any of this reaches down to the earliest stage end of the market, including SEIS eligible companies experimenting with tokenised shareholdings. That gap is explored separately in our Open Question piece today.
Key takeaways
The FCA and Bank of England received 123 responses to their May 2026 Call for Input and will publish a full tokenisation roadmap, with workstreams and target dates, later in 2026.
Industry's clearest request was to move beyond time limited sandboxes to permanent market infrastructure; the FCA has committed to a defined path from the DSS to permanent authorisation.
Post-trade and collateral management were identified as the biggest near term opportunity, including tokenised money market funds used as collateral without liquidation.
A consultation on custody rules for relevant specified investment cryptoassets is planned for the first half of 2027; CASS 6 applies in the meantime.
The FCA reaffirmed a technology neutral, same risk same regulatory outcome approach, while ruling out arrangements that leave customers without recourse if assets are lost.
Sources
Frequently asked questions
What is the FCA and Bank of England Feedback Statement FS26/1?
FS26/1 is a joint Feedback Statement published by the FCA and the Bank of England on 14 September. It summarises 123 responses to their May 2026 Call for Input on the future of tokenisation in UK wholesale financial markets.
What happens after the UK Digital Securities Sandbox ends?
The FCA has committed to a clear path from the Digital Securities Sandbox to permanent authorisation. It will work with the Treasury to consider whether to extend or modify the sandbox, or amend the wider Central Securities Depositories Regulation framework, and will publish a fuller roadmap with workstreams and target dates later in 2026.
Can stablecoins be used in the UK Digital Securities Sandbox?
Yes. The FCA confirmed that stablecoins can be used within the Digital Securities Sandbox, subject to conditions and pending Treasury amendments.
Which FCA custody rules apply to tokenised securities?
The FCA plans to consult on safeguarding rules for relevant specified investment cryptoassets in the first half of 2027. Until then, firms operating in the space will continue to be assessed under the existing CASS 6 client asset rules.
How does the FCA treat tokenised assets for prudential purposes?
The FCA said tokenised versions of traditional assets should generally receive equivalent treatment to their non-tokenised counterparts, provided legal rights are identical and underlying risks are comparable.


Comments