
What the UK tokenisation feedback means for your business

Updated: 7 days ago
Tokenisation and the new UK regime · Part 1 of 6
FS26/1 changes no rules. Its value to a founder or platform is that it shows which parts of a tokenisation plan can go ahead on today's rules, and which still depend on decisions to come.
Palvinder Gill, Principal, Insight Regulatory Consulting Limited and Founder of cryptopru.com UK position checked on 26 September 2026.
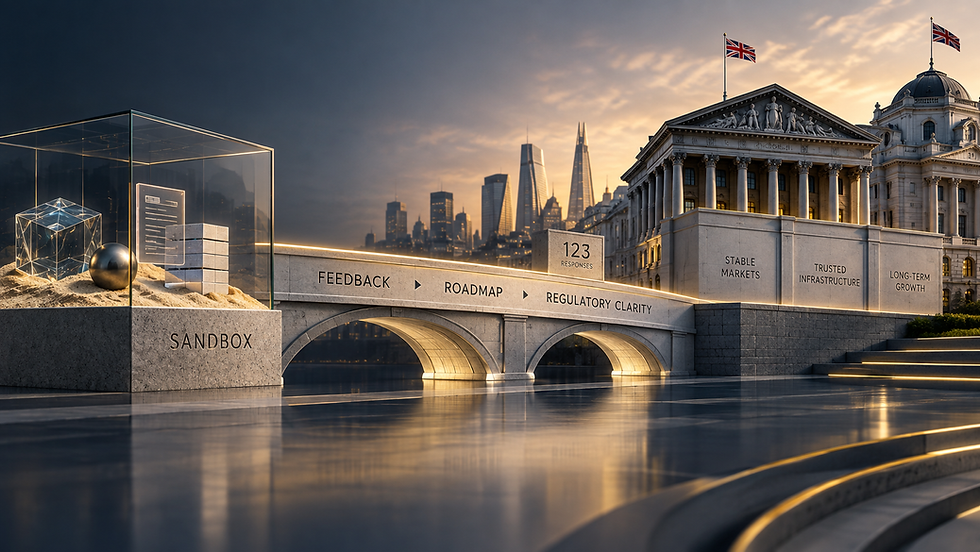
For a founder, the useful question is which parts of a tokenisation plan can proceed now and which still depend on regulatory decisions. FS26/1 helps identify those dependencies. It is the FCA and Bank of England's summary of 123 responses to their May 2026 Call for Input on tokenisation in wholesale financial markets (FS26/1, 1.1 and 1.6). Tokenising Startups was one of the respondents. Its scope is wholesale markets, so it says little directly about early-stage equity, but several of its positions shape what a tokenisation business can build.
A feedback statement is not a rule change. The existing rules continue to apply. The authorities will publish a Tokenisation Roadmap later this year with planned changes and dates (FS26/1, 1.5 and 1.8). Each change will still need its own legal instrument to take effect.
Running example (fictional, illustrative, not a legal determination). Company A is a UK private company that plans to issue shares in token form. Platform P will maintain the token record and hold investors' tokens. Supplier K provides key management to P. The later articles change one fact at a time to show which question each fact raises.
What the authorities have settled
The perimeter is not changing. Regulated activities stay with regulated firms. Those firms may use third-party technology, including under outsourcing arrangements, but they keep responsibility for outcomes such as operational resilience and KYC (FS26/1, Chapter 2 response). Calling a service "technology" does not settle its regulatory status. A provider's own activities may still need permission (Parts 2 and 6).
For traditional investment products, the authorities "cannot accept solutions where customers have no recourse when assets are lost or stolen" (FS26/1, Chapter 2 response). This is about legal recourse. It is not a promise that lost assets can always be recovered technically.
Custody of tokenised securities is assessed under the existing CASS 6 rules for now. The FCA will consult on additional safeguarding rules for these assets in the first half of 2027 (FS26/1, 1.10 and Chapter 3 response). Part 3 covers custody.
The authorities agree that collateral is the main near-term use. They will not deprioritise primary issuance, which they link to their growth objectives (FS26/1, Chapter 2 response).
What still depends on decisions to come
Settlement in stablecoins. The authorities have confirmed that stablecoins can be used as settlement assets in the Digital Securities Sandbox (DSS), subject to conditions and to Treasury amendments to the regulations (FS26/1, Chapter 3 response).
Settlement finality. Respondents argued that contractual finality does not give the protection against third parties in insolvency that statutory finality under the Settlement Finality Regulations provides. The authorities are considering what further certainty they can give (FS26/1, 3.7 and response).
Prudential treatment. The PRA's May 2026 Dear CEO letter says that, for PRA-regulated firms, tokenised traditional assets should in general receive the same prudential treatment as their non-tokenised equivalents where legal rights are identical and risks are comparable. Respondents asked what "comparable" means, and timelines will come in the Roadmap (FS26/1, 3.4 to 3.5).
Tokenised collateral at central counterparties. The Bank will consult later this year. Separately, the FCA will look further at synthetic tokens and digital twins (FS26/1, Chapter 2 responses).
The DSS offers a route to permanent authorisation, and its end state will be shaped by what the sandbox shows (FS26/1, Chapter 3 response). Firms taking part gain direct operating evidence. Firms outside it can contribute through consultations, and the authorities invite firms to raise specific blockers with them (FS26/1, 1.11).
Practical judgement (the author's view, not an FCA position). A structure in which the token is itself the security keeps the link between issuer and investor that the authorities want to preserve (FS26/1, 2.6). That is a structuring judgement, not regulatory approval of one design. Whatever the structure, the firm should be able to answer three questions: who owes the investor what, which record evidences the investor's entitlement, and which counterparty fails if the structure breaks.
Deciding what can proceed now
The chief executive and product lead should write a one-page dependency note before committing development spend. It should record the proposed service, the target customer, who owns the permission analysis, the settlement assumption and any reliance on future policy. Mark each dependency as available now, conditional or unresolved, with an owner and a trigger for review.
Legal and compliance should classify the token and the firm's activities before a permission list is fixed, using the method in Part 2.
If permission may be needed, the application lead should start the evidence tracker described in Part 5. It is easier to build as decisions are made than to reconstruct later.
Put the dated milestones in the plan and check each one at publication: the Roadmap and the Bank's consultation on central counterparty collateral, both expected later this year, and the FCA's consultation on custody of tokenised securities in the first half of 2027.
The Field Guide on cryptopru.com summarises each of the FCA's final cryptoasset policy statements for readers who need the underlying rules.
Key takeaways
FS26/1 changes no rules. Continue to apply the current rules, track the Roadmap for planned changes, and check the legal instrument that gives each change effect.
The perimeter is unchanged, and custody of tokenised securities is assessed under CASS 6 for now. A technology label does not decide regulatory status.
Stablecoin settlement, settlement finality and prudential equivalence are still conditional. Record them as dependencies with owners.
Sources
FCA and Bank of England, FS26/1, Tokenisation in Wholesale Financial Markets, September 2026.
FCA and Bank of England, The future of tokenisation: a joint vision for UK wholesale financial markets, Call for Input, May 2026.
PRA, Dear CEO letter on cryptoasset exposures, May 2026.
Frequently asked questions
What is the FCA and Bank of England feedback statement FS26/1?
FS26/1 is the FCA and Bank of England's summary of 123 responses to their May 2026 Call for Input on tokenisation in wholesale financial markets. It is a feedback statement, not a rule change, so the existing rules continue to apply.
When will the UK Tokenisation Roadmap be published?
According to FS26/1, the FCA and Bank of England will publish a Tokenisation Roadmap later this year with planned changes and dates. Each change will still need its own legal instrument to take effect.
Which UK rules apply to custody of tokenised securities?
Custody of tokenised securities is assessed under the existing CASS 6 rules for now. The FCA will consult on additional safeguarding rules for these assets in the first half of 2027.
Can stablecoins be used for settlement in the UK Digital Securities Sandbox?
The authorities have confirmed that stablecoins can be used as settlement assets in the Digital Securities Sandbox, subject to conditions and to Treasury amendments to the regulations. This remains a conditional dependency rather than a settled position.
Do tokenised assets get the same prudential treatment as traditional assets in the UK?
The PRA's May 2026 Dear CEO letter says that, for PRA-regulated firms, tokenised traditional assets should in general receive the same prudential treatment as their non-tokenised equivalents where legal rights are identical and risks are comparable. Respondents asked what comparable means, and timelines are due in the Roadmap.
This is general information, not legal, tax or investment advice.
Next: Part 2, Does your tokenised share need cryptoasset permission?
Palvinder Gill is Principal of Insight Regulatory and runs cryptopru.com, a free toolkit for firms preparing FCA cryptoasset applications, to which this article refers.

Comments